Social Security Survivor Benefits 2026: Eligibility, Amounts, and Claiming Rules
September 22, 2026
A Clear Guide for Spouses, Ex-Spouses, and Families
How eligibility, claiming age, work, remarriage, family limits, benefit switching, and current 2026 rules can affect monthly payments
Featured illustration: Survivor-benefit eligibility depends on relationship, timing, and application rules.
Social Security is not only a retirement program. A worker’s covered earnings can also provide monthly protection to eligible family members after the worker dies, including a spouse, former spouse, child, or dependent parent. [1]
The rules differ from ordinary retirement and spousal benefits. A surviving spouse may be able to start at 60, qualify earlier because of disability, claim at any age while caring for an eligible child, or coordinate survivor benefits with a personal retirement benefit. Work and remarriage can also change eligibility or payment timing. [1,2]
Key takeaways
- A surviving spouse can generally qualify at age 60, or at 50–59 if disabled, subject to marriage and other requirements. [1]
- A surviving divorced spouse may qualify when the marriage lasted at least 10 years; special caregiving rules can apply regardless of age. [1]
- A spouse’s payment can start at 71.5% at age 60 and rise to as much as 100% at survivor full retirement age. [2]
- Survivor and personal retirement benefits are not added together, but a claimant may be able to start one and switch to the other later. [2]
- For 2026, work before full retirement age can trigger withholding above $24,480, or above $65,160 in the year retirement full retirement age is reached. [3,4]
- WEP and GPO no longer reduce benefits payable for January 2024 and later under the Social Security Fairness Act. [9]
- Monthly survivor benefits cannot currently be applied for online; the separate $255 lump-sum payment has its own application and two-year deadline. [7,8]
| Accuracy and date scope: This article reflects SSA rules and 2026 earnings-test figures available on September 1, 2026. It distinguishes survivor full retirement age from retirement full retirement age and incorporates the repeal of WEP and GPO for benefits payable from January 2024 forward. [3,4,9] |
Who may qualify
The deceased worker must have enough Social Security-covered work for insured status. The number of credits needed depends on age at death, and some families of younger workers can qualify under a special recent-work rule. [10]
| Potential survivor | General eligibility starting point | Important qualification |
|---|---|---|
| Surviving spouse | Age 60+, or 50–59 if disabled | Marriage generally lasted at least 9 months; exceptions exist; remarriage timing matters. |
| Surviving divorced spouse | Age 60+, or 50–59 if disabled | Marriage generally lasted at least 10 years; deceased worker’s remarriage does not block eligibility. |
| Caregiving spouse or ex-spouse | Any age may qualify | Caring for the deceased worker’s entitled child who is under 16 or disabled; relationship rules differ. |
| Child | Usually unmarried and under 18 | May qualify at 18–19 if full-time K–12 student, or at any age for disability beginning before 22. |
| Dependent parent | Age 62+ | Deceased worker generally provided at least one-half of the parent’s support. |
Table note: SSA applies detailed relationship, dependency, disability, school-attendance, and insured-status rules. This table gives the first screening question, not a benefit determination. [1,10]
The nine-month marriage rule for a current spouse and the ten-year rule for an ex-spouse both have exceptions and definitions. A person should not assume a short marriage or nontraditional legal relationship is automatically disqualifying without checking the SSA rule that matches the facts. [1,10]
How much can a surviving spouse receive?
For a surviving spouse or qualifying ex-spouse, payments generally start at 71.5% at age 60 and increase for each month claiming is delayed. The amount can reach up to 100% at survivor full retirement age, which falls between 66 and 67 depending on birth year. [2]
The percentage is not always a simple percentage of the deceased worker’s last check. The worker’s claiming history, the widow or widower limit, the family maximum, and the survivor’s own filing age can affect the payable amount. SSA’s estimate is therefore more reliable than multiplying a bank deposit by 71.5% or 100%. [2,10]
| Simplified illustration: If the relevant unreduced worker amount were $2,400, 71.5% is $1,716 and 100% is $2,400. This is orientation only; it does not incorporate the deceased worker’s claiming history, earnings-test withholding, family maximum, or other SSA adjustments. [2] |
Survivor benefits versus a personal retirement benefit
A person eligible for both benefits generally receives one payment equal to the higher available amount, not two full checks added together. Survivor rules allow switching strategies that are not available in the same way for ordinary spouse benefits. [2]
| Feature | Survivor benefit | Own retirement benefit |
|---|---|---|
| Earliest common start | Age 60; age 50 if disabled | Age 62 |
| Age for maximum under normal timing | Survivor FRA (66–67) | Age 70 after delayed retirement credits |
| Can the two full amounts be added? | No—one combined payment generally equals the higher available amount | No |
| Can a later switch be possible? | Yes; survivor first, retirement later is one possible sequence | Yes; retirement first, survivor later can also fit some cases |
| Earnings-test FRA used | Retirement FRA, even if survivor FRA is earlier | Retirement FRA |
Table note: The best sequence depends on actual benefit estimates, birth date, work, and claiming month. Survivor benefits stop increasing at survivor FRA; own retirement benefits can grow through age 70. [2,3]
One possible sequence is to start a survivor benefit and switch to a larger personal retirement benefit at 70. Another is to start a smaller personal benefit and switch to a larger survivor benefit at survivor FRA. The higher current payment is not always the higher lifetime sequence. [2]
Survivor and retirement benefits generally do not stack, but a later switch may be possible.
Working while receiving survivor benefits in 2026
Only earned income—generally wages and net earnings from self-employment—counts for the annual earnings test. Pensions, investment income, and most other non-work income do not count as earnings for this test. [3]
| 2026 work situation | Earnings limit | Withholding rule |
|---|---|---|
| Under retirement FRA for all of 2026 | $24,480 | $1 withheld for every $2 above the limit |
| Reaches retirement FRA during 2026 | $65,160 before the FRA month | $1 withheld for every $3 above the limit |
| At/after retirement FRA | No annual limit | Earnings test no longer withholds benefits |
| Table note: For survivor benefits, SSA uses the full retirement age applicable to retirement benefits for the earnings test, even when survivor FRA is earlier. [3,4] |
Withholding under the earnings test is temporary rather than a separate tax. At full retirement age, SSA recalculates the benefit to credit months in which benefits were withheld because of excess earnings. The timing of the withheld checks can still matter for near-term cash flow. [3]
How remarriage affects eligibility
Remarriage before age 60 generally blocks survivor benefits on a prior deceased spouse’s record while the later marriage continues. For an eligible disabled surviving spouse, the comparable threshold is generally age 50 and additional conditions apply. [1,5]
Remarriage after age 60 generally does not prevent survivor benefits on the prior deceased spouse’s record. If a remarriage before 60 later ends by death, divorce, or annulment, eligibility on the earlier record may be restored when the other requirements are met. [5]
| Timing matters: A remarriage at 59 and a remarriage at 60 can produce different survivor-eligibility results. Disabled-survivor rules add another branch, so use the exact marriage date, disability timing, and benefit category. [5] |
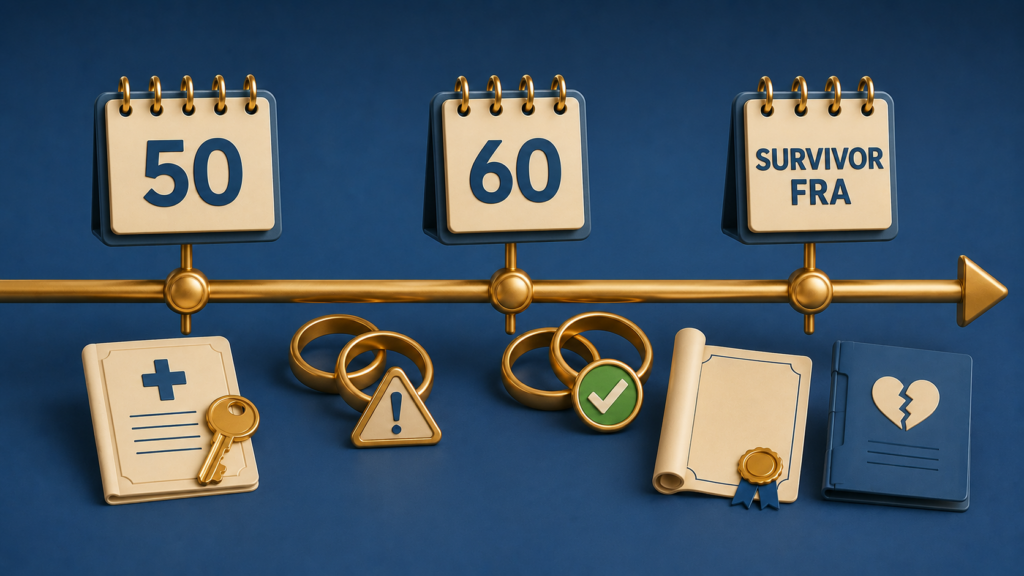
Age, disability status, and the timing of remarriage can change survivor-benefit eligibility.
The family maximum
When several family members qualify on one worker’s record, Social Security limits the total monthly amount. The retirement-and-survivor family maximum generally falls around 150% to 180% of the worker’s full retirement benefit, although the statutory formula—not a flat percentage—controls. [6]
If calculated benefits exceed the maximum, benefits for family members can be reduced. Benefits paid to a qualifying divorced spouse generally do not reduce the amounts payable to other family members, and ex-spouse payments generally do not count toward the family maximum. [2,6]
Current law for government pensions: WEP and GPO were repealed
The Social Security Fairness Act, signed January 5, 2025, repealed the Windfall Elimination Provision and Government Pension Offset. SSA states that WEP and GPO no longer apply to benefits payable for January 2024 and later, including surviving-spouse benefits that previously could have been reduced by GPO. [9]
A non-covered government pension can still matter for taxes, Medicare premiums, or other programs, but it no longer triggers the WEP/GPO Social Security reductions for current benefit months. Articles or calculators that still automatically apply GPO to post-2023 survivor benefits are outdated. [9]
What to do after a death
A funeral home usually reports the death to SSA, but death reporting and a monthly survivor claim are different steps. Monthly survivor benefits cannot currently be applied for online; SSA directs claimants to call or work with a local office. A person already receiving spouse benefits may be converted automatically to survivor benefits after the death is processed. [7]
The one-time $255 lump-sum death payment is separate. SSA’s current page provides an online application route for that payment, and a qualifying spouse or child generally must apply within two years of the death. Automatic conversion from spouse to survivor benefits should not be treated as proof that the lump sum was claimed. [7,8]
| Do not wait for perfect paperwork: SSA advises beginning the claim even if every document is not yet available. The effective date and retroactivity rules depend on the benefit and filing facts, so an eligible person should not assume all missed months will be paid automatically. [10] |
Documents SSA may request
- Proof of death, such as a death certificate or funeral-home statement. [10]
- The applicant’s and deceased worker’s Social Security numbers and proof of age. [10]
- Marriage certificate or divorce decree for spouse or ex-spouse claims. [10]
- Birth certificates and Social Security numbers for dependent children. [10]
- The worker’s recent W-2 or federal self-employment return and the applicant’s bank information. [10]
A practical survivor-benefit checklist
- List every potentially eligible spouse, ex-spouse, child, and dependent parent. [1]
- Record marriage, divorce, remarriage, birth, disability, school, and caregiving dates. [1,5]
- Estimate the survivor benefit at age 60, at survivor FRA, and at relevant months between them. [2]
- Compare the survivor timeline with the claimant’s own retirement benefit through age 70. [2]
- If working, compare expected 2026 earnings with the correct limit and retirement FRA. [3,4]
- Check whether several eligible relatives could trigger the family maximum. [6]
- Confirm that no outdated WEP/GPO reduction is being applied to benefits payable after December 2023. [9]
- Treat monthly benefits and the $255 lump sum as separate application questions. [7,8]
Frequently asked questions
Can someone receive a full survivor benefit and full personal retirement benefit at the same time?
No. The two full amounts are not added together. SSA generally pays an amount equal to the higher available benefit, although switching from one benefit to the other later may be possible. [2]
Can a former spouse receive survivor benefits?
Yes. A surviving divorced spouse may qualify when the marriage generally lasted at least 10 years and the age, disability, marital-status, and other requirements are met. The deceased worker’s remarriage does not itself block the claim. [1,7]
Does remarriage always end eligibility?
No. Remarriage before 60 generally blocks benefits on the prior deceased spouse’s record while that marriage continues; remarriage after 60 generally does not. Disabled-survivor rules can use age 50 and additional conditions. [5]
Can someone work and receive survivor benefits?
Yes, but payments may be withheld under the earnings test before retirement full retirement age. The 2026 limits are $24,480 and, in the year retirement FRA is reached, $65,160 for earnings before the FRA month. [3,4]
Can monthly survivor benefits be applied for online?
No. SSA currently handles monthly survivor claims by phone or through a Social Security office. The separate lump-sum death payment has its own application route. [7,8]
Is the $255 death payment automatic?
Do not assume it is. A qualifying spouse or child generally must apply within two years. Automatic conversion of an existing spouse benefit to a survivor benefit is a separate process. [7,8]
Final takeaway
Social Security survivor benefits are a family protection system, not one standard widow’s benefit. The most consequential variables are the claimant category and the dates: claiming age, survivor FRA, retirement age 70, marriage duration, remarriage, disability, caregiving, and work before retirement FRA. Putting those facts on one timeline makes the available benefit sequences easier to compare and helps expose outdated assumptions.
Claim notes and fact-checking record
| Verification scope: Eligibility, benefit-percentage, remarriage, work, application, and 2026-dollar claims were checked against current SSA pages and publications. The article removes the obsolete assumption that WEP/GPO still reduce current survivor benefits. |
| Marker | Primary-source support |
|---|---|
| [1] | SSA — Who can get Survivor benefits — Current eligibility overview for spouses, ex-spouses, children, and dependent parents. |
| [2] | SSA — What you could get from Survivor benefits — Confirms 71.5%–100% spouse amounts, child percentages, one-payment rule, switching, and family-maximum basics. |
| [3] | SSA — Receiving benefits while working — Explains earnings counted, 2026 withholding rules, recalculation, and use of retirement FRA for survivor earnings testing. |
| [4] | SSA — 2026 COLA fact sheet — Confirms the 2026 $24,480 and $65,160 retirement earnings-test limits. |
| [5] | SSA — Will remarriage affect my benefits? — Explains remarriage timing, disabled-survivor rules, and restoration after a later marriage ends. |
| [6] | SSA — Family maximum FAQ — Explains the approximate 150%–180% family range and the treatment of divorced-spouse benefits. |
| [7] | SSA — Survivor Benefits: Protection for Your Family (2026) — Confirms current application method, automatic spouse-to-survivor conversion, non-stacking, and the separate lump-sum question. |
| [8] | SSA — Lump-sum death payment — Confirms the $255 amount, eligible spouse/child framework, online application route, and two-year filing deadline. |
| [9] | SSA — Social Security Fairness Act: WEP and GPO update — Confirms repeal of WEP and GPO for benefits payable from January 2024 onward. |
| [10] | SSA Publication 05-10084 — Survivors Benefits — Detailed official guide to insured status, marriage and dependency rules, benefit amounts, documents, and filing considerations. |
| Educational use only: This article provides general educational information, not individualized tax, legal, Social Security, or investment advice. Rules, forms, agency interpretations, and individual outcomes can change. Use the official materials for the applicable year and facts. |